Our latest data update looks at national GP, specialist and consultant physician attendances through August 2026, measured as rolling 12-month totals.
1. Our read of August 2026
The three segments are moving in different directions.
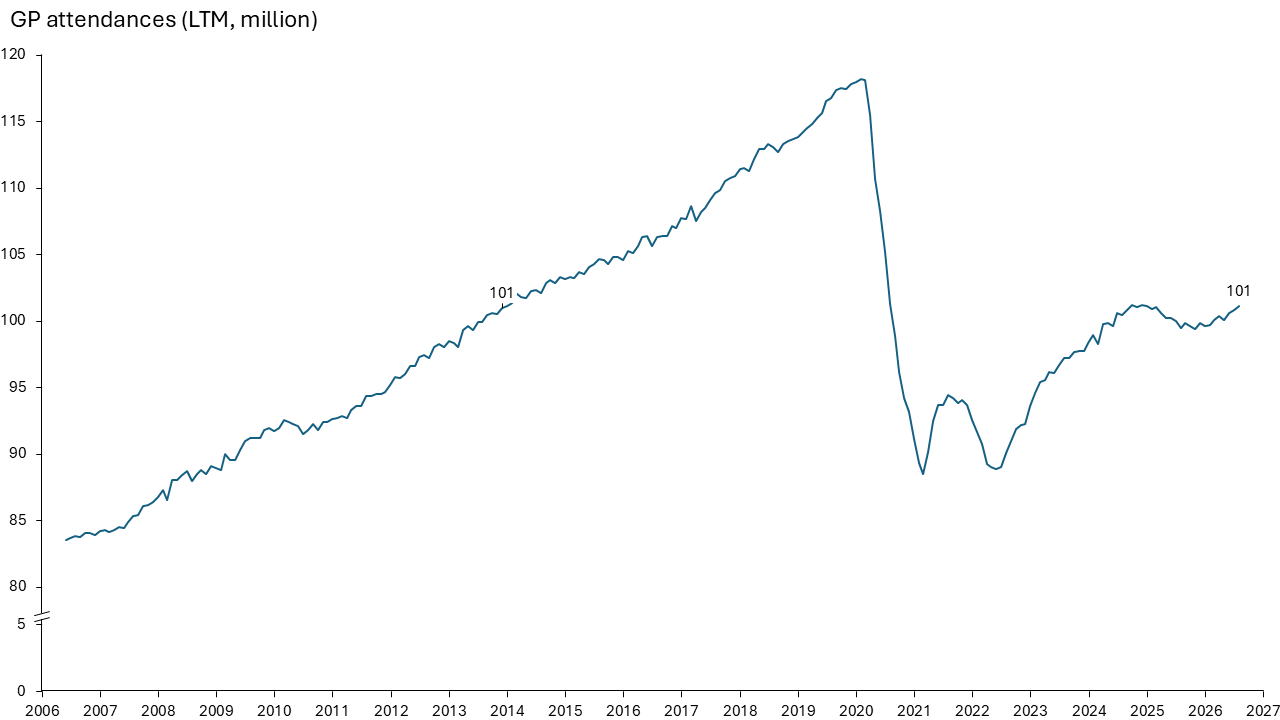
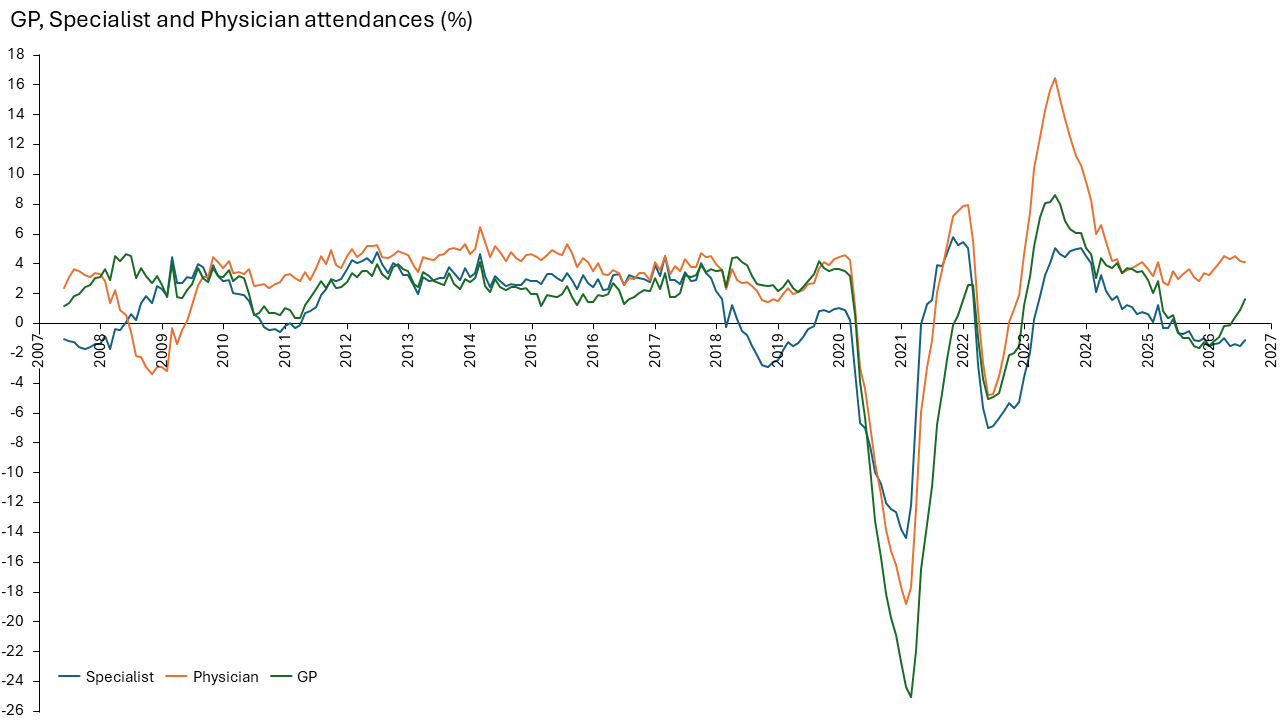
- GP attendances are growing again. After slipping into decline through 2025, annual GP volume has climbed back to about 101 million, and growth has turned from roughly -1.5% late last year to about +1.6%. The timing fits the expanded bulk-billing incentives that started in November 2025, though it is too early to say how much they explain. Even so, GP volume sits around 15% below its early-2020 peak, at about the same level as 2014.
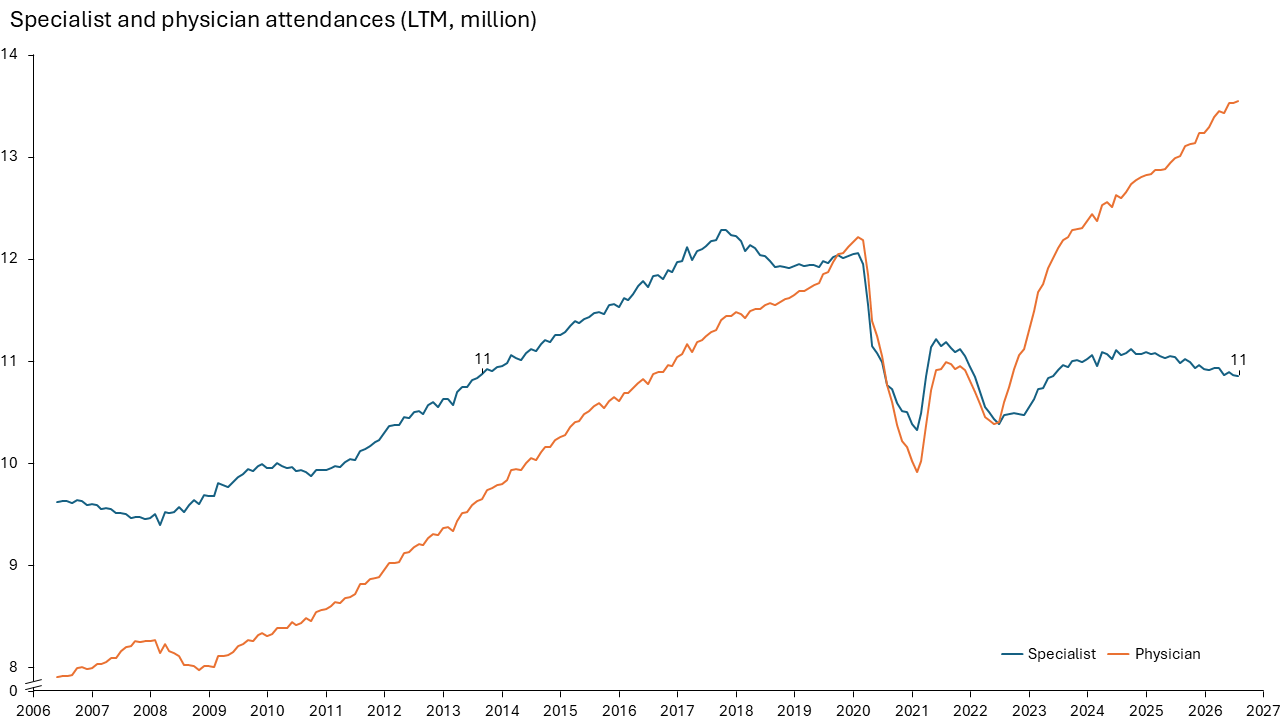
- Specialist attendances are drifting lower. Annual specialist consults have edged down from about 11.1 million in 2024 to around 10.9 million. They have now been falling for roughly 18 months and are running about 1% below last year. Specialist volume is lower than it was a decade ago and well below its 2017 high of about 12.3 million.
- Consultant physician attendances keep setting records. Physician volume has reached about 13.6 million a year, roughly 11% above its pre-COVID peak. Growth has held steady at about 4%, in line with its long-run average, as ageing and chronic disease keep demand rising.
Because these are rolling 12-month figures, they move slowly. The turnaround in GP volume is likely stronger month to month than the headline number shows.
2. What this means for practice owners
- GP: demand is returning after a long reset. Growth is back, but GP volume remains about 15% below its pre-COVID peak. That gap reflects structural changes in how GP care is delivered, including telehealth, longer consults and new channels like urgent care clinics, rather than a lack of GPs. For practice owners, the questions are how much of the recent recovery is incentive-driven, what it does to revenue per consult as bulk-billing mix shifts, and whether appointment structures still match how patients now use general practice.
- Specialist: the referral pool is shrinking. Fewer consults means more competition for each GP referral. Referral relationships, wait times and how easy a practice is to refer to will decide who grows in a market that is gently shrinking.
- Physician: the growth segment, with no sign of slowing. Steady 4% growth sustained over 15 years is unusual in healthcare. The limiting factor is physician workforce. Practices that can recruit and support physicians, including through allied health and nurse-led chronic care, have a clear runway.
We will keep tracking these series monthly alongside our private surgery index.
Next steps
Connect with us to learn how Practice Alliance can help your practice.